Positioning Yourself for the Next Wave of Wealth Creation
TL;DR: The next major cycle of wealth creation is already forming, driven by technology, real estate appreciation, and compounding asset ownership. Whether you participate only as a worker and consumer or also as an owner will determine how much of that growth reaches you.
Key Takeaways
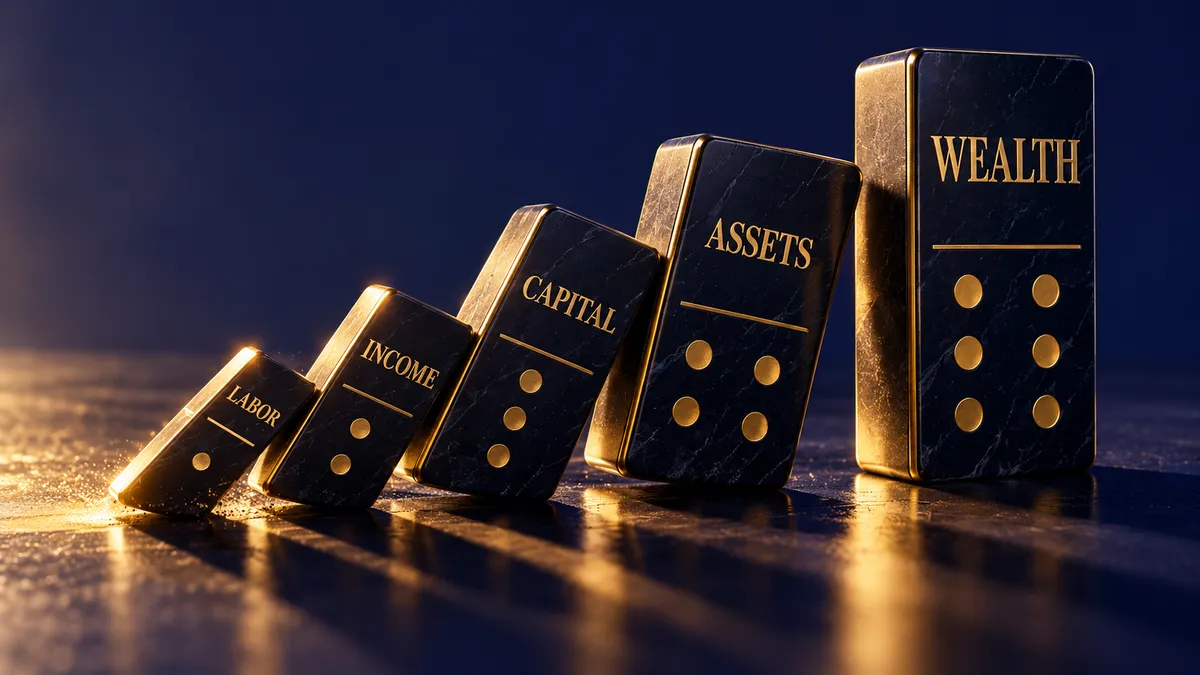
The wealth-building progression runs in order: labor creates income, income creates capital, capital acquires assets, and assets create wealth.
Recent data shows household wealth accelerating through financial assets and real estate. Ownership determines who participates in that growth.
U.S. homeowners collectively hold approximately $35.5 trillion in home equity, with roughly $11.5 trillion considered tappable. That is a strategic resource, not just a number on a balance sheet.
AI, robotics, energy, and biotechnology may be creating another major economic transformation, comparable in scope to the Industrial Revolution, the automobile era, and the internet.
A significant generational wealth transfer is forming as Baby Boomers begin downsizing and transferring real estate holdings. The capital that moves will be substantial.
You work hard for your money. But here is the question that matters far more to your long-term financial future:
How much of the money you earn is eventually working for you?
Every paycheck gives you a choice. Some of that money will pay for today's lifestyle. Some can be converted into capital that buys assets. Those assets can then begin growing alongside you, potentially creating an entirely different financial future.
That distinction is becoming increasingly important.
We are seeing tremendous amounts of wealth being created through stocks, real estate, businesses, and emerging technologies. If you already own these assets, you may be watching your net worth grow. If you do not, you may be working just as hard while watching the value of those assets move further away from you.
That is why one of the most important financial questions you can ask yourself in 2026 is not simply:
"How can I earn more?"
It is:
"How can I turn more of what I earn into assets I own?"
What Is the Labor-to-Wealth Progression?
There is a simple sequence that explains how most lasting wealth is built:
Labor creates income. Income creates capital. Capital acquires assets. Assets create wealth.
Each step builds on the one before it. Labor is where most people start. It is the mechanism through which income is generated and capital is accumulated. But the progression matters because labor alone has a ceiling. The hours in a day are finite. The value of those hours is subject to market conditions. And income that is consumed rather than converted into ownership does not compound.
Assets compound.
Recent wealth data showed another acceleration in U.S. household wealth, driven in large part by financial assets and real estate. Investors have seen the effect in their portfolios, while homeowners have continued to benefit from the equity accumulated over the past several years.
But the important lesson is not simply that asset values have risen. It is that ownership determines who participates in that growth.
Why Labor Is the Starting Point, Not the Destination
For most people, wealth creation begins with labor.
We go to work. We build businesses. We develop skills. We solve problems and create value in exchange for income.
There is nothing wrong with that. In fact, labor is what gives most people the capital to begin building wealth. But income alone is not wealth.
It is what you do with that income that determines your financial trajectory. The objective is to consistently convert some portion of today's labor into assets that have the potential to grow tomorrow.
Eventually, you want your assets working alongside you. Over time, you want them doing more and more of the work.
The process: Earn. Save. Deploy. Own. Compound. Repeat.
Are We Entering a Major Wealth-Creation Cycle in 2026?
This concept becomes especially significant when the economy goes through periods of major technological change.
Think about previous economic transformations:
The Industrial Revolution created entirely new industries and fortunes.
The automobile transformed manufacturing, transportation, energy, construction, and real estate.
The internet created companies and business models that barely existed a generation earlier.
Artificial intelligence may be the most visible example of that kind of transformation today, but it is hardly the only one. Robotics, advanced manufacturing, energy, biotechnology, computing, and automation are changing how businesses operate and how value is created.
AI and the technologies developing around it may be creating another significant wave of economic opportunity.
When productivity increases and businesses become more valuable, much of that wealth ultimately accrues to the people who own the assets. The question becomes whether you participate in these economic changes only as a worker and consumer or whether you also participate as an owner.
How Much Home Equity Do American Homeowners Hold?
For millions of Americans, their largest asset is not in a brokerage account. It is the home they live in.
U.S. homeowners collectively hold approximately $35.5 trillion in home equity, with roughly $11.5 trillion considered tappable equity. That is the portion homeowners could potentially access while still maintaining a substantial ownership position in their properties.
That represents an extraordinary amount of household wealth. For many families, it was accumulated quietly over decades through mortgage payments and appreciation.
But there is an important distinction between having wealth and strategically managing wealth. Home equity increases your net worth, but equity sitting inside a property generally does not create spendable monthly cash flow by itself.
That certainly does not mean homeowners should automatically borrow against their homes. In many situations, leaving that equity untouched may be exactly the right decision. The point is that it deserves to be part of the broader financial conversation.
How Can Homeowners Use Home Equity as Strategic Capital?
The strategic questions worth asking about home equity are not borrowing questions. They are planning questions.
Could a portion of accumulated equity eventually help acquire another property?
Could it fund improvements that increase the value or income potential of the existing property?
Could it replace expensive consumer debt, improving monthly cash flow and creating an opportunity to redirect those dollars toward investments?
Could it provide capital for a business or another productive asset?
The right answer will be different for every household. But these are the kinds of questions that separate passive equity accumulation from active wealth management.
What Is the Coming Generational Wealth Transfer?
There is another major shift developing beneath the surface that deserves attention.
A significant amount of America's real estate wealth is concentrated among older generations, particularly Baby Boomers and the Silent Generation. For decades, these households accumulated wealth through homeownership.
As they begin selling properties, downsizing, relocating, or eventually transferring assets to their families, an enormous amount of housing wealth could begin moving through the economy.
As it does, we could see:
Long-held properties returning to the market
Substantial wealth transferred to younger generations
Capital redeployed into investments, businesses, additional real estate, and other assets
That movement of capital could become one of the largest generational wealth transitions in American history. The people positioned to receive and deploy that capital will have a significant advantage.
How Do You Start Converting Income into Wealth in 2026?
This brings us back to the original question: How much of the money you earn is eventually working for you?
Wealth creation is not simply about earning more. It is about what happens after you earn it.
Take a look at your own financial position. How much of your income is being converted into assets each month? What assets are you intentionally accumulating? If you own real estate, how much equity have you built, and does that equity fit into your broader financial strategy?
There is no universal formula. But there should be a strategy.
We may be entering a period in which technology, productivity, business ownership, financial markets, and real estate create significant opportunities for wealth creation. Those opportunities will not benefit everyone equally. They will disproportionately benefit people who own assets and have positioned themselves to participate.
Labor is the starting point. Ownership is the destination.
Frequently Asked Questions
What is the difference between income and wealth?
Income is money earned through labor, business activity, or investment returns. Wealth is accumulated ownership of assets, including real estate, businesses, financial instruments, and other stores of value. Income that is consumed rather than converted into ownership does not compound over time. Wealth does. The transition from income earner to asset owner is what drives most significant long-term financial outcomes.
What is tappable home equity?
Tappable equity refers to the portion of a homeowner's equity that could be accessed, typically through a home equity line of credit or a cash-out refinance, while still maintaining at least 20% equity in the property. As of recent data, U.S. homeowners hold approximately $11.5 trillion in tappable equity. Whether and how to access it depends entirely on each household's financial position, goals, and risk tolerance.
Is AI creating a new wealth opportunity like the internet did?
Historically, major technological shifts, including the Industrial Revolution, the rise of the automobile, and the growth of the internet, created substantial wealth for people who owned the assets and businesses that benefited from those changes. AI and related technologies are driving productivity gains and business value creation in ways that may follow a similar pattern. Participation in those gains is more likely for people who hold ownership stakes in the companies, assets, or infrastructure involved.
Ready to look at where you stand and what moves make sense from here?
At Peak Capital Mortgage, we start with a full financial picture before recommending any product or strategy. Your equity, your income, your goals, and your timeline all factor in.
Talk to Us About Your Financial Position
Rich Flanery, Broker Owner | Peak Capital Mortgage LLC | NMLS #256117 | Company NMLS #2347925