HELOC for Debt Consolidation: A Smarter Approach in 2026
TL;DR: Many homeowners are sitting on significant equity while paying 23% or more on credit card debt. A HELOC can replace that expensive debt with lower-cost borrowing, potentially saving hundreds of dollars per month in interest, without touching an existing first mortgage rate.
Key Takeaways
U.S. homeowners hold trillions in home equity while many of those same households are paying 23% or more in interest on credit card balances.
A HELOC lets qualifying homeowners access that equity as a separate revolving line of credit, without changing the rate or terms on an existing first mortgage.
Consolidating $40,000 in credit card debt from 23% to a HELOC at 9% can save roughly $467 per month in interest, or about $5,600 per year.
The strategy only works when borrowers stop accumulating new consumer debt and commit to a concrete repayment plan.
The right question is not how much equity you have. It is whether your current financial structure is actually working for you.
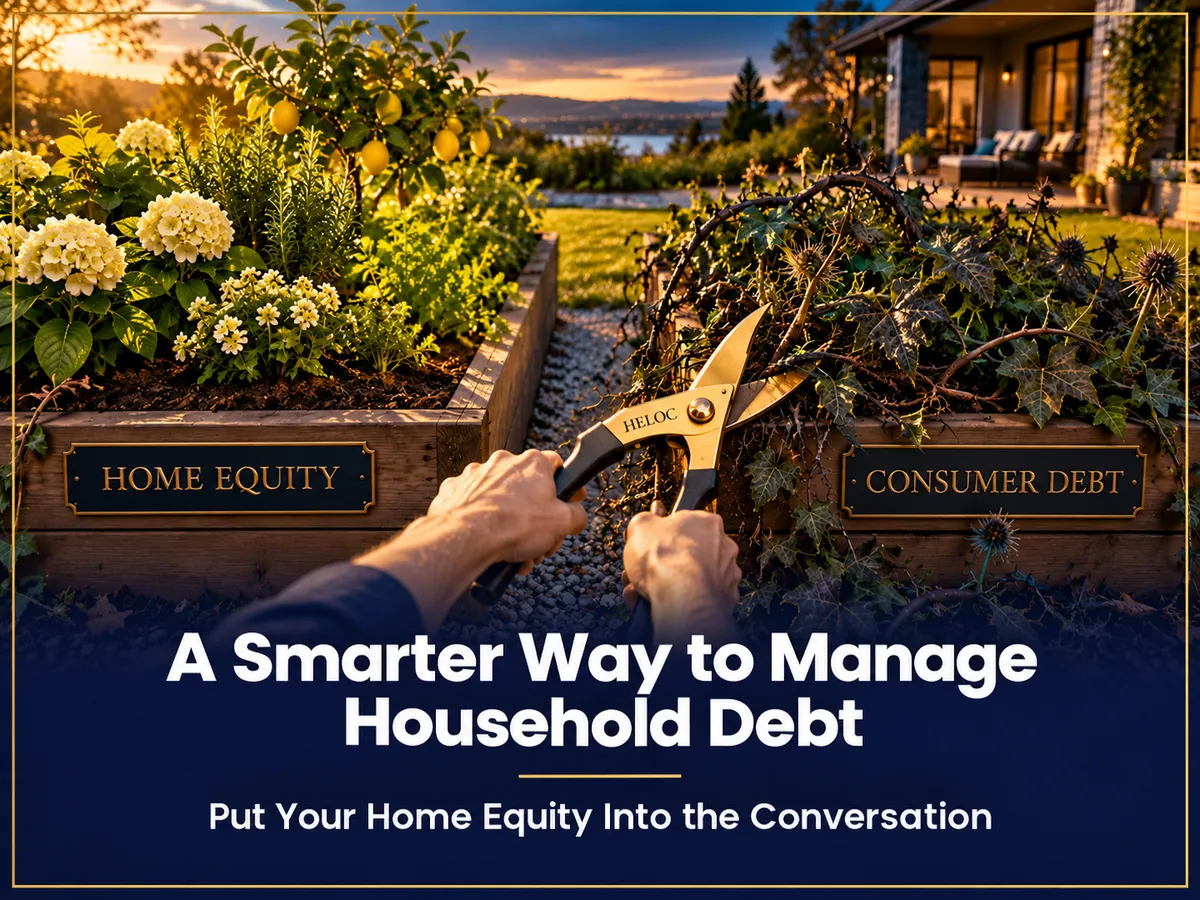
In 2026, American homeowners are living inside a financial paradox. Home equity is at record levels. Consumer debt is also at record levels. Many households are sitting on substantial wealth in their property while simultaneously paying some of the most expensive debt they have ever carried.
A HELOC, used with discipline and a clear plan, can bridge those two realities. But it is not a product for every borrower, and those who use it without understanding the mechanics can make an already difficult situation worse.
What Is a HELOC and How Does It Work?
A HELOC, or Home Equity Line of Credit, is a revolving line of credit that allows qualifying homeowners to borrow against a portion of the equity they have built in their property. The credit limit is based on the difference between the home's current market value and the outstanding mortgage balance.
Unlike a traditional installment loan, a HELOC functions more like a credit card backed by your home. During the draw period, you can access funds up to your approved limit, pay interest only on what you actually borrow, and repay and re-borrow as needed.
A HELOC is typically structured as a separate second lien, sitting alongside your primary mortgage. That separation matters: you can access equity without touching the rate or terms on your existing first mortgage.
HELOC structures vary. Some carry variable interest rates tied to the prime rate. Others allow borrowers to lock portions of their balance into a fixed rate. Terms, fees, and qualifying requirements differ by lender, which is one reason shopping multiple options makes a meaningful difference.
Can You Use a HELOC to Pay Off Credit Card Debt?
Yes. Using a HELOC to consolidate high-interest credit card debt is one of the most common applications of home equity borrowing. The strategy replaces expensive consumer debt, often carrying rates of 23% or more, with home equity borrowing at a substantially lower rate.
The interest rate on a HELOC is typically far below what credit card companies charge. That gap, applied to significant balances, translates directly into lower monthly interest costs, and for borrowers who redirect those savings toward the principal, a faster path to eliminating the debt.
The word to focus on is "consolidate," not "eliminate." Moving balances from a credit card to a HELOC does not make the debt disappear. It changes the cost of carrying that debt, which changes the math on paying it off, but only if the spending behavior that created the debt changes alongside it.
How Much Could You Save by Consolidating Debt with a HELOC?
The savings depend on the rate difference and the size of the balance.
Consider a household carrying $40,000 in credit card debt at 23% interest. The monthly interest cost on that balance is approximately $767. At an illustrative HELOC rate of 9%, that same $40,000 balance generates roughly $300 per month in interest. The difference is approximately $467 per month, or about $5,600 over a full year.
That figure represents interest saved, not principal reduced. The real opportunity is what happens when the household redirects that $467 toward paying down the balance. As the principal decreases, the monthly interest cost decreases, which frees up more cash to accelerate repayment. That compounding effect is where the strategy produces its most meaningful long-term results.
Actual savings depend on the HELOC rate a borrower qualifies for, the fees associated with opening the line, the repayment structure selected, and how quickly the balance is reduced. These numbers illustrate the concept. A proper analysis uses your actual figures.
Does a HELOC Affect Your Existing Mortgage Rate?
No. A HELOC is established as a separate loan and does not change the terms of your existing first mortgage. Your current rate, monthly payment, and amortization schedule remain exactly as they are.
This is particularly relevant in 2026. Many homeowners locked in first mortgages at rates significantly below current market levels. Refinancing the entire mortgage simply to access equity would mean giving up those favorable terms. A HELOC lets them reach their equity without disturbing a rate they worked to secure.
This is one of the primary reasons HELOCs are receiving more attention right now. They offer a path to equity access that does not require replacing a loan you are better off keeping.
What Are the Risks of Using a HELOC for Debt Consolidation?
The primary risk is behavioral. If you pay off credit cards with HELOC funds and then carry new balances on those same cards, you have turned one debt problem into two. The HELOC balance remains while new consumer debt rebuilds. That outcome leaves you in a worse position than you started.
There is also a structural consideration worth understanding. A HELOC uses your home as collateral. Credit card debt, while expensive, is unsecured. Defaulting on a credit card is financially damaging. Defaulting on a HELOC carries the risk of foreclosure. Moving debt from unsecured to secured changes the consequences of non-payment, and borrowers should make that trade with clear eyes.
Variable rates are a third factor. A HELOC tied to the prime rate adjusts as market conditions change. Borrowers should model what their payments would look like if rates move upward during the repayment period and build that scenario into their plan.
The answer to all three risks is the same: begin with a specific written repayment plan and the discipline to execute it.
Who Should Consider Using Home Equity to Manage Household Debt?
The right candidates are homeowners who have meaningful equity, a stable income, high-interest consumer debt, and a genuine commitment to a repayment plan.
The conversation should start with a financial analysis, not a loan application. The questions worth answering before opening a HELOC include:
What are your current balances and interest rates?
How much of each monthly payment is going toward interest versus reducing the principal?
How much equity is available, and how does the HELOC repayment fit into the household budget?
What is the concrete plan to eliminate the debt, and what spending changes will support it?
Homeowners who cannot clearly answer those questions are not ready for this product. The HELOC is a tool. The plan determines whether the tool produces the result you want.
Frequently Asked Questions
What is the difference between a HELOC and a cash-out refinance?
A cash-out refinance replaces your existing mortgage with a new, larger mortgage. You receive the difference in cash and begin repaying the new loan at the current market rate. A HELOC is a separate second lien that sits alongside your existing mortgage. Your first mortgage stays in place, with its original rate and terms unchanged. For homeowners who want equity access without giving up a low existing rate, a HELOC is generally the more appropriate tool.
How much equity do you need to qualify for a HELOC in 2026?
Most lenders require that your combined loan-to-value ratio, meaning your first mortgage balance plus the HELOC limit divided by the appraised home value, stays at or below 80% to 85%. Some lenders allow higher thresholds depending on the borrower's credit profile and property type. Reviewing your current mortgage balance and getting a current value estimate on your home will give you a reasonable starting point.
Is HELOC interest tax deductible?
Under current tax law, HELOC interest is deductible only when the funds are used to buy, build, or substantially improve the home securing the loan. Using HELOC proceeds for debt consolidation generally does not qualify for the mortgage interest deduction. Tax treatment is specific to each borrower's situation and can change with legislation. Consult a qualified tax professional before making assumptions about deductibility.
Ready to see what your home equity could do for your monthly cash flow?
At Peak Capital Mortgage, we start with a full financial analysis before recommending any product. We want to understand your current rates, balances, and goals before we discuss solutions.
Find Out What Your Equity Could Do
Rich Flanery, Broker Owner | Peak Capital Mortgage LLC | NMLS #256117 | Company NMLS #2347925