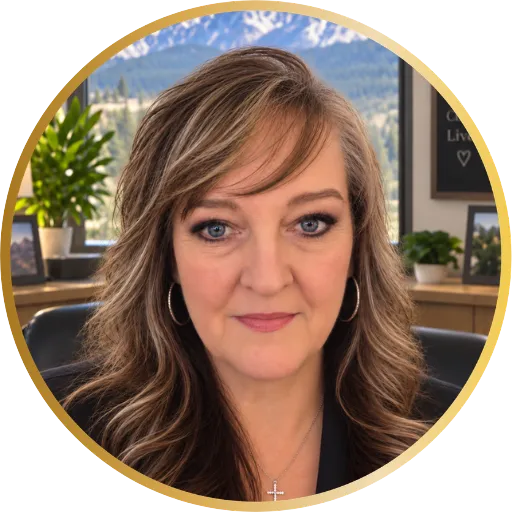
Reva Haskin
Senior Loan Officer
(970) 235-0668
[email protected]
Reva is a seasoned mortgage professional with over 18 years of experience helping clients achieve their homeownership and investment goals. At Peak Capital Mortgage, she specializes in complex financing solutions, investment properties, and guiding veterans through the unique benefits of VA financing. Every loan she structures is tailored to the specific needs and circumstances of her clients.
Her approach goes far beyond securing a competitive rate. Reva provides clear communication, expert guidance through every stage of the process, and personalized support from the first conversation to the closing table. Whether it's a first home, an addition to an investment portfolio, a challenging financial scenario, or navigating VA loan requirements, she is dedicated to making the experience as smooth and stress-free as possible.
Reva combines convenience with decades of proven expertise. She has spent more than 10 years in volunteer leadership roles that strengthen families and communities, a passion that fuels her commitment to service.
Guided by a favorite Paulo Coelho quote, "When you want something, all the universe conspires in helping you achieve it," Reva brings dedication, knowledge, and care to every client she serves.
To read more about how Reva works with veterans and complex loan scenarios across Texas, Colorado, New Mexico, and Arizona, including the real stories behind her approach, read her full feature article.
NMLS 196123 License: AZ 1009629 | CO 100033541 | NM | KS LO.0053299 | TX
What Clients Say About Reva
Reva consistently earns praise for her persistence, her availability, and her ability to make complex financing feel manageable. Every review below was written by a client on Google.
"Reva was absolutely amazing! Thank you for being with us every step of the way and always going above and beyond for us!!"
Ruth L. · Peak Capital Client
"What really made our experience unforgettable was Reva. Words can't express how grateful we are for her hard work. She focused so heavily on our loan, keeping us updated every step of the way, answering every question quickly, and keeping the process moving flawlessly. Reva's level of care and commitment is rare."
Yuliia L. · Peak Capital Client
"Reva has been exceptional at explaining all of our options. If we have any questions she is quick to respond and over all just a pleasure to work with."
Brian L. · Peak Capital Client
"This was our second time buying a home with Reva as our mortgage officer. She will go to bat for you and make sure the deal is a good fit for you. Professional and patient 20/10!!!"
Nickole M. · Repeat Client
"Reva was absolutely incredible through the entire process! Always available to answer questions, explained every step, and was so helpful. She made it so smooth for us. Highly recommend!"
Lindsey S. · Peak Capital Client
"Reva is truly one of a kind! She is incredibly hardworking, reliable, and always there with answers and reassurance. Her dedication and professionalism make the entire process smoother and far less stressful."
Brittney S. · Peak Capital Client
Reviews are published by clients on Google and reflect those individuals' experiences. They are not a guarantee of any particular outcome, timeline, or result. Loan approval, program eligibility, and closing timelines vary by borrower, property, loan program, lender, and market conditions. Peak Capital Mortgage LLC, NMLS #2347925. Equal Housing Opportunity. This is not a commitment to lend.
Where Reva Does Her Best Work
When other lenders say no
Eighteen years in, the files that reach Reva are rarely the simple ones. Veterans using a benefit they have used before. Borrowers whose income is real but does not look like a pay stub. Buyers who need to compete against cash. Here is where that experience matters most.
✓VA financing, start to finish
Entitlement, funding fee treatment, reuse of the benefit on a second purchase, and the property conditions that trip up a VA file late in the process. Reva has walked veterans and active duty buyers through all of it, including the scenarios that get bounced elsewhere.
✓Income that does not fit a W2
Self-employed borrowers, oil and gas and energy sector earners, and agricultural income. The money is there. The challenge is documenting it the way an underwriter needs to see it, and structuring the file so the income counts.
✓Pre-underwriting before you shop
In a competitive market, a pre-qualification letter is not much of an argument. Reva sends the file through underwriting up front so your offer carries real weight with a listing agent, and so the surprises show up before you are under contract.
✓The file someone already turned down
A no from one lender is one lender's guidelines, not a verdict. Sometimes the answer is a different program. Sometimes it is a two step plan: get the house now, then revisit the financing once the circumstances that caused the problem have changed.
How I Work
Most of what reaches my desk has already been somewhere else. A veteran was told the entitlement would not work. A self-employed borrower was told the tax returns did not support the payment. A buyer keeps losing houses to offers that look stronger on paper. By the time we talk, the person on the other end of the phone is usually tired of being told no.
So I start with the whole picture instead of the application. What does the income actually look like across a couple of years, where is it coming from, and what does an underwriter need to see to count it? That conversation takes longer at the front. It also means far fewer problems in the middle, which is where most loans fall apart.
From there we pick the program that fits the situation rather than the one that is easiest to quote. VA, FHA, USDA, conventional, and investment property financing all sit in front of me, and they behave very differently once a file gets complicated. When it makes sense, I will run the file through underwriting before you write an offer, so the strength is real and the surprises come out early.
I work across the DFW corridor and Midland in Texas, the Western Slope of Colorado including Mesa, Delta and Garfield counties, San Juan County in New Mexico, and Maricopa County in Arizona. Some of that is rural, some of it is fast and competitive, and the two need very different handling.
If someone has already told you no, tell me what they said. That is usually the most useful sentence in the whole conversation.

Stay Ahead with , Your Weekly Financial Newsletter
Take the Next Step?
Choose Your Path Forward
About Us
Our success has been built on competitive rates designed to meet your unique financing goals while delivering exceptional customer service. At Peak Capital Mortgage LLC, we pride ourselves on treating every client with honesty and integrity.
Company NMLS: 2347925
Licensed in: AL, AZ, CO, FL, ID, KS, LA, MI, MS, MT, NM, SD, TX and WY
Navigation
Important Links
This is not a commitment to lend. All loans subject to underwriter approval. Terms and conditions apply, subject to change without notice


© Copyright 2026. Peak Capital Mortgage LLC. All Rights Reserved.